The federal domestic gas reservation scheme explained
Key Findings
The government’s domestic reservation scheme aims to fix the troubled eastern Australia gas market, where high gas prices have pushed up energy costs, contributed to inflation and driven industrial closures.
High gas prices in eastern Australia have contributed to higher inflation and industrial closures.
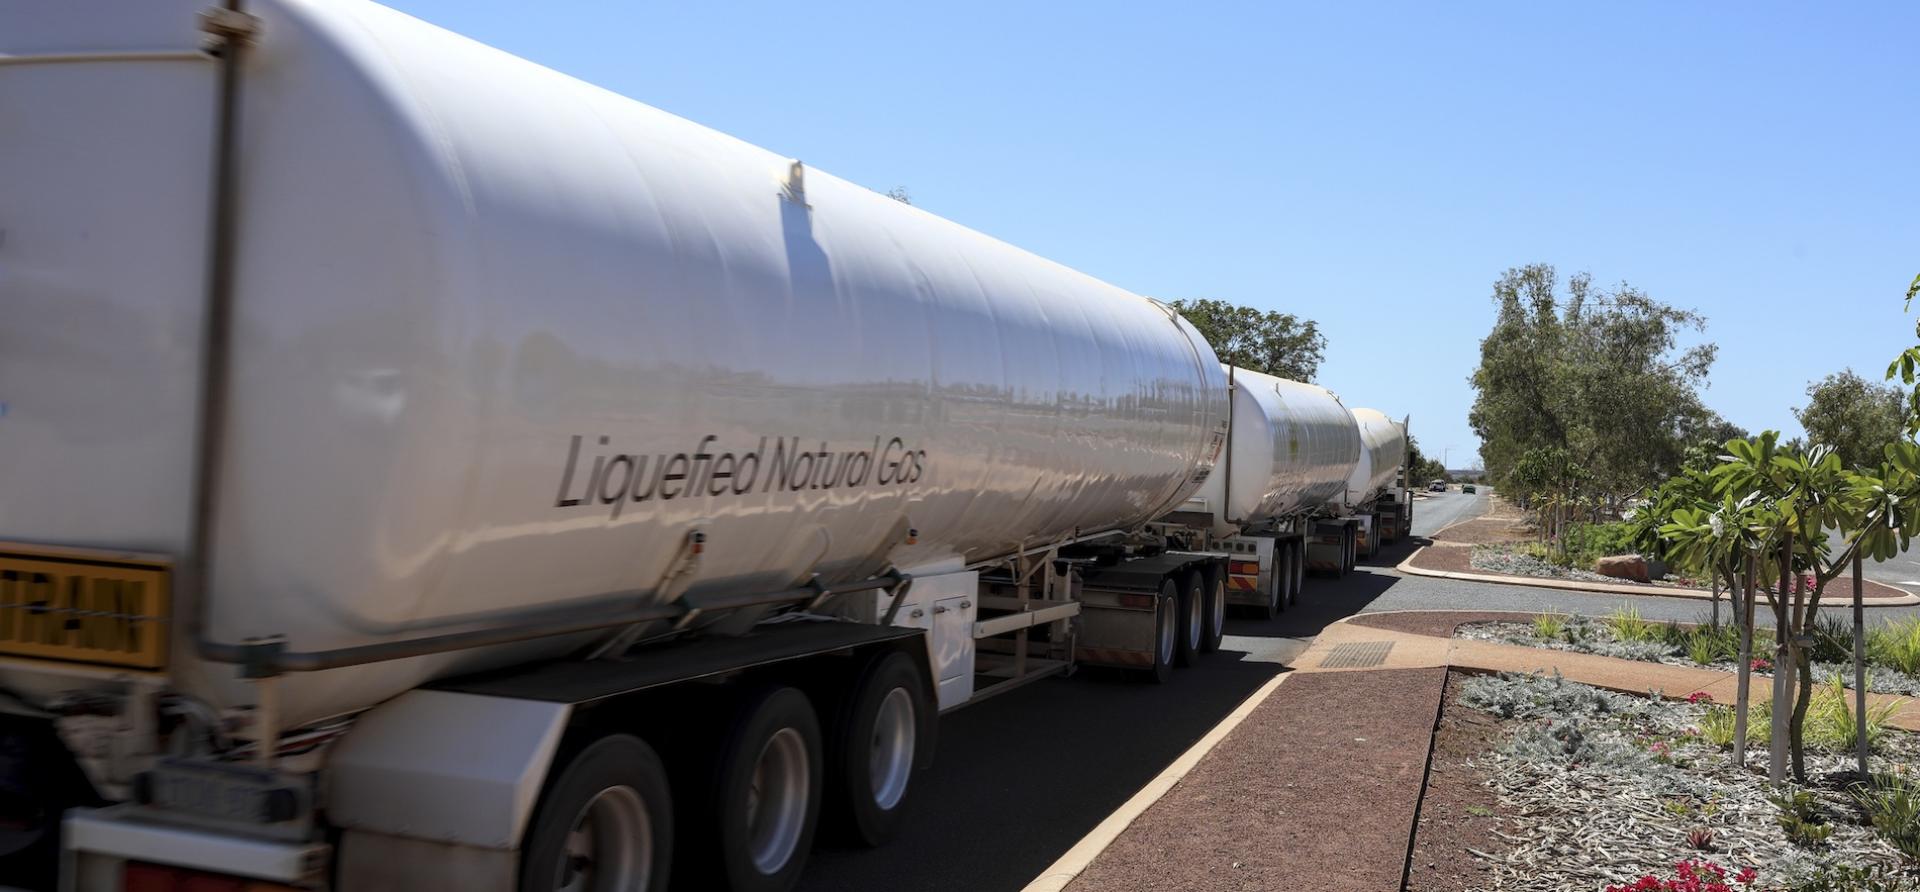
The reservation scheme would impose domestic supply obligations (DSOs) on Australian LNG exporters, meaning they may need to supply domestically if they want to export LNG.
Why this is important?
- The government’s domestic reservation scheme represents its most drastic intervention to fix the troubled east coast gas market.
- High gas prices in eastern Australia have pushed up energy costs, contributed to inflation and driven industrial closures.
- Australian gas markets face forecast shortfalls even as Australia is a major exporter of liquefied natural gas (LNG).
The issue of gas reservation, particularly in Australia’s troubled east coast gas market, has become a regular fixture in media headlines over the past year. Gas users point to the adverse impacts of LNG exports on domestic markets to support the need for reservation, while the gas industry (with some exceptions) argues that greater investment in new gas supply is a better option.
Why is the Australian government implementing a reservation policy?
Gas prices in eastern Australia were historically low due to abundant supplies of low-cost gas from offshore Victoria.
Over the past decade, gas prices have increased materially for two main reasons: Victorian gas production from legacy fields is declining and producers are turning to more marginal (and more costly) fields; and the start of LNG exports from Queensland exposed the domestic market to higher international prices.
The impact has been felt across the economy, with higher gas prices driving up costs for households, major industrial users and electricity markets. This has added to inflationary pressures and led to industrial closures.
The Australian government has implemented a range of policy measures over the past decade, including the Australian Domestic Gas Security Mechanism (that would allow exports to be diverted in the event of a shortfall) and a Gas Market Code of Conduct.
These measures have not worked in the way the government had hoped, and a 2025 Gas Market Review recommended a new gas reservation scheme.
How will the reservation scheme work?
The reservation will work by imposing domestic supply obligations (DSOs) on Australian LNG exporters, set to maximum of 20% of their LNG export volumes in a given regulated period (i.e. year). This will be implemented through a framework that requires export licences to export LNG, with licences potentially being revoked where exporters do not comply with DSOs. Put simply, an exporter may need to supply domestically if it wants to export LNG.
As part of an annual process, the Minister for Resources will set each exporter’s DSO based on a range of factors, including domestic demand. It is unlikely that DSOs will not be set at 20% of exports, at least not in the early years of the scheme. In Western Australia and the Northern Territory, there is the prospect that DSOs will be set at zero when the market is well supplied.
The Minister will have the authority to set exporter DSOs in a way that achieves a “moderate” oversupply of up to 110% of forecast demand, which is intended to reduce prices but may raise issues around the physical ability of the market to absorb that supply. The scheme allows exporters the flexibility to supply only 90% of their DSO in a given period, but it’s not clear if this will be sufficient to address physical capacity risks.
Individual exporter DSOs can also be adjusted to protect existing LNG export contracts, to account for existing state reservation schemes and where there are infrastructure constraints.
What are the key sticking points?
Several elements of the reservation scheme have proven particularly contentious.
The first relates to the impact on different Queensland exporters. Origin’s Australia Pacific LNG project has been adamant that all three exporters need to contribute to ensuring sufficient domestic supply. It specifically points to Santos’s Gladstone LNG (GLNG) plant, which has historically relied on purchasing from the domestic market to meet its obligations, stating it should not be carved out due to insufficient gas supplies.
Without securing sufficient gas, GLNG may not be able to extend one of its LNG contracts, due to expire in 2031 but extendable to 2036, and comply with DSO requirements. This could potentially lead to GLNG closing down one of its two LNG liquefaction units, but Santos and GLNG may explore other options, including new supply and reservation carveouts, to avoid this occurring.
The flexibility afforded to exporters remains another point of tension. The design allows exporters to purchase “additional” gas from domestic gas producers without impacting on DSO requirements, where that gas otherwise would not have been extracted.
However, this raises an obvious issue: how can government identify which gas is actually additional? The plan is for the Australian Energy Regulator to take on this unenviable task, and it is not yet clear how the regulator will overcome information asymmetries between it and gas producers and therefore address the risks of gaming of the market.
The potential for oversupply is a key concern for domestic only gas producers, who argue it will depress gas prices and undermine investment in new gas supplies. There are also broader concerns that the policy does not explicitly seek to improve investment in new supply
The policy has also raised concerns in countries that purchase Australian LNG. The South Korean, Japanese, Malaysian and Chinese governments have all made representations to protect their interests in Australian LNG supply. A looming LNG supply glut does not appear to have assuaged their concerns.
Finally, the policy has led to tensions between the federal and West Australia state governments, with the latter arguing that its existing reservation policy is working and there is no need for additional regulation. It appears this argument has only partially landed given the Minister for Resources will retain the ability to impose DSOs on West Australian exporters.
Fewer concerns have been expressed by domestic gas users, who are likely to benefit from greater supply and lower prices, provided the scheme works as intended. The intervention appears to already be working, as GLNG has reduced domestic purchases and this has already reduced prices.
First published in The Energy.
Related Content