Rising costs and financing risks derail emerging Asia’s LNG-to-power expansion
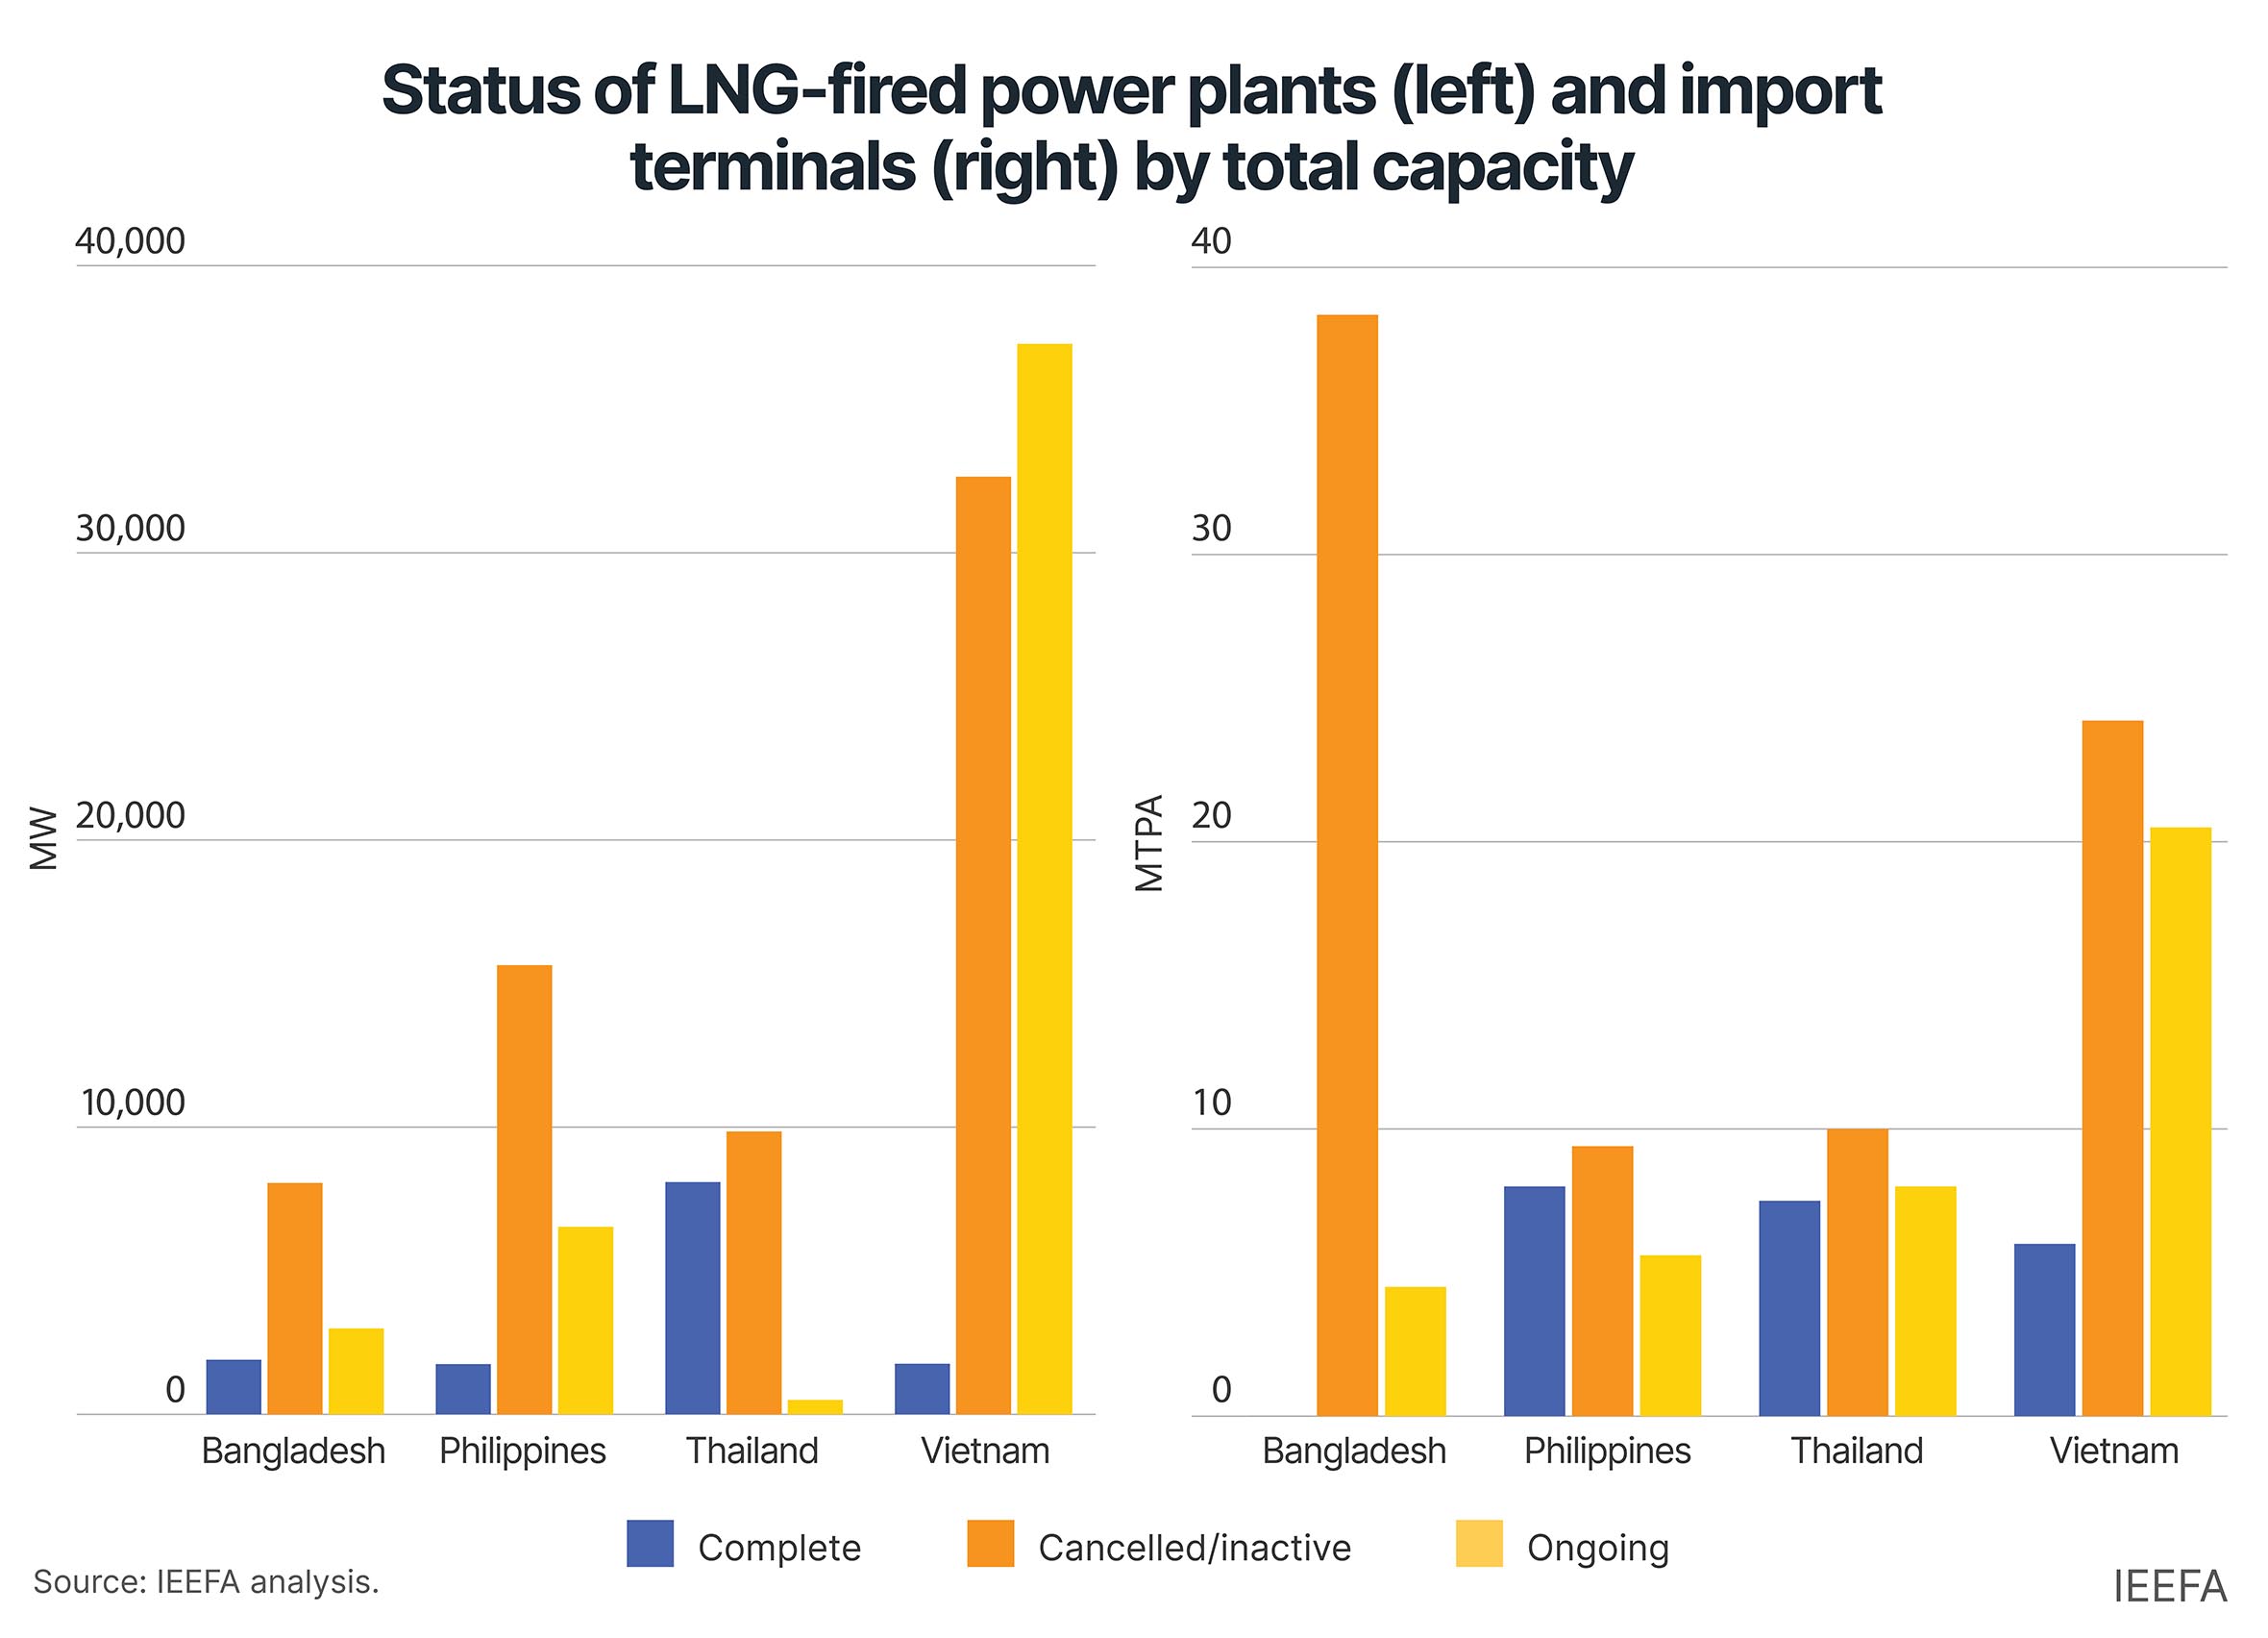
Since 2021, over half of proposed LNG-fired power plants and import terminals in key emerging markets have been canceled or are inactive, with a combined value 4.5 times that of completed projects.
November 5, 2026 (IEEFA Asia): More than half of proposed liquefied natural gas (LNG)-fired power projects and import terminals across the Philippines, Vietnam, Thailand, and Bangladesh were canceled or showed no notable progress between 2021 and 2026, according to a new report by the Institute for Energy Economics and Financial Analysis (IEEFA).
In these four markets, IEEFA surveyed 92 proposed LNG-fired power projects worth an estimated USD109.2 billion and 44 LNG import terminals valued at USD21 billion.
The report identified 49 proposed LNG-fired power plants and 22 regasification terminals that have been canceled or shown no notable progress between 2021 and 2026, with an estimated total value of USD67.8 billion. This is nearly 4.5 times the value of projects completed during the same period.
“Recent developments in fuel, equipment, and currency markets have exacerbated execution risks for LNG-to-power projects in emerging Asian economies while weakening the revenue certainty needed to secure project financing,” says Sam Reynolds, co-author of the report and IEEFA Asia’s LNG/Gas Research Lead. “As a result, the region’s LNG expansion has progressed far more slowly than the global gas industry expected.”
Despite a substantial pipeline of proposed LNG power plants and import terminals, only 11% of proposed power generation capacity and 15% of import terminal capacity in the four markets came online between 2021 and 2026. This is a substantially lower completion rate than IEEFA estimated in a 2021 analysis of the commercial feasibility of LNG-to-power projects in the region.
Moreover, completed power projects took more than seven years on average to reach commercial operations, far longer than the three-to-four-year estimates often claimed by project developers.
Volatile costs and renewables competition increase financial risks for LNG-to-power projects
Since 2021, extreme LNG price volatility, higher capital costs, longer lead times for gas turbines, and the depreciation of emerging Asian currencies against the US dollar have undermined the financial viability of LNG-to-power projects and hindered bankability.
“Taken together, these risks could increase the total levelized cost of electricity from LNG-fired power plants by up to 130% relative to baseline assumptions in 2021,” according to report co-author Christopher Doleman, IEEFA Asia’s LNG/Gas Specialist.
“Across emerging Asia, energy-sector development plans that rely heavily on LNG were often formulated on assumptions of lower fuel prices and affordable capital costs. Those assumptions no longer hold.”
Global LNG prices have remained well above pre-2020 averages due to Russia’s full-scale invasion of Ukraine in 2022, followed by the outbreak of the Middle East conflict in 2026. In September 2026, spot market prices in Asia reached USD27.5 per million British thermal units, nearly three times pre-conflict levels.
Along with fuel price volatility, a global shortage of gas turbines is widely expected to increase capital costs for new LNG-fired power plants and delay the construction of numerous projects in emerging Asia. Capital costs for recent gas projects in the United States, for example, have increased nearly fourfold since 2022. Delivery timelines for heavy-duty turbines now extend to six years or more.
Meanwhile, falling costs and faster rollout timelines for renewable technologies such as solar and wind are reducing the need for LNG-fired power plants in baseload roles. Battery storage deployments could shorten the periods when LNG is needed for peaking power. Together, these trends increase the risk of underutilization for the region’s gas infrastructure.
Country case studies reveal LNG financing challenges in practice
The report also provides detailed case studies for each of the four countries surveyed.
For example, the Philippines has faced a high rate of project cancellations since 2021, due largely to a failure to win creditworthy offtake agreements with distribution utilities. The growth of renewable energy projects has also complicated dispatch dynamics for fossil fuel assets, while the lack of demand in non-power sectors hinders the commercial viability of new LNG import terminals.
Despite Vietnam’s ambitious LNG-to-power targets, only one LNG-fired power project has reached commercial operations in the last five years. Persistent challenges concerning the bankability of power contracts have created significant barriers to investment, while LNG cost escalation amid uncertain tariff recovery threatens the state-owned utility’s financial health.
Thailand recorded more progress in completing gas-fired projects but continues to face significant underuse of existing gas plants and LNG terminals.
Bangladesh has completed three LNG-fired power plants since 2021, but high LNG and power costs have increased government subsidy burdens and deepened reliance on external financing to preserve foreign-exchange reserves. Yet the country continues to face gas shortages due to unreliable LNG supplies.
“In each market, the investment case for new projects is becoming more difficult due to higher US dollar-denominated fuel and capital costs, alongside increasing competition from renewable technologies,” says Doleman.
“National market conditions differ, but the underlying financial and operational risks for LNG-to-power projects are similar throughout the region,” says Reynolds. “Ultimately, the poor track record for LNG-to-power projects since 2021 suggests that expectations for rapid LNG demand growth in emerging Asia may be disconnected from on-the-ground project outcomes.”
Read the report: LNG-to-power in emerging Asia: A five-year review of project outcomes
Author contacts:
Sam Reynolds ([email protected])
Christopher Doleman ([email protected])
Media contact:
Alex Yu ([email protected])