Heat on steelmakers to ditch carbon for electrons
Key Takeaways:
Electrification will be a major theme at COP31, and the steel industry needs to consider all available electrification opportunities to reduce emissions while strengthening long-term cost-effectiveness, supply-chain resilience and energy security.
While much of the focus has been on decarbonising primary steelmaking, significant opportunities exist in secondary steelmaking and the electrification of heat across the value chain, which could further reduce sector emissions.
Flexibility is a key advantage of electrification technologies, allowing steelmakers to reduce energy consumption during peak periods, and shift production towards periods of low-cost, low-emissions electricity.
Hydrogen will be essential for iron ore reduction, but it may not be the preferred alternative for heat generation, where its efficiency is likely to be lower than direct electrification.
23 October 2026 (IEEFA Australia): The electrification of global steelmaking should expand to all facets of production, driven by technological advances and soaring energy costs, according to a report released today.
As the Middle East crisis hits global fuel supplies and prices, the push to decarbonise the heavily fossil fuel-reliant steel industry is extending from primary steelmaking to high-temperature heat processes, finds the report Electrification across the steel value chain.
“Steel production is one of the most energy-intensive industrial processes,” says the author Soroush Basirat, IEEFA’s energy finance analyst, global steel.
“Energy use in the sector is primarily driven by the chemical energy needed to reduce iron ore into iron, and the high-temperature heat required across the steelmaking value chain.
“Electrification can address both, and should be prioritised as a key pathway to reduce emissions, fossil fuel dependence and exposure to energy supply risks.”
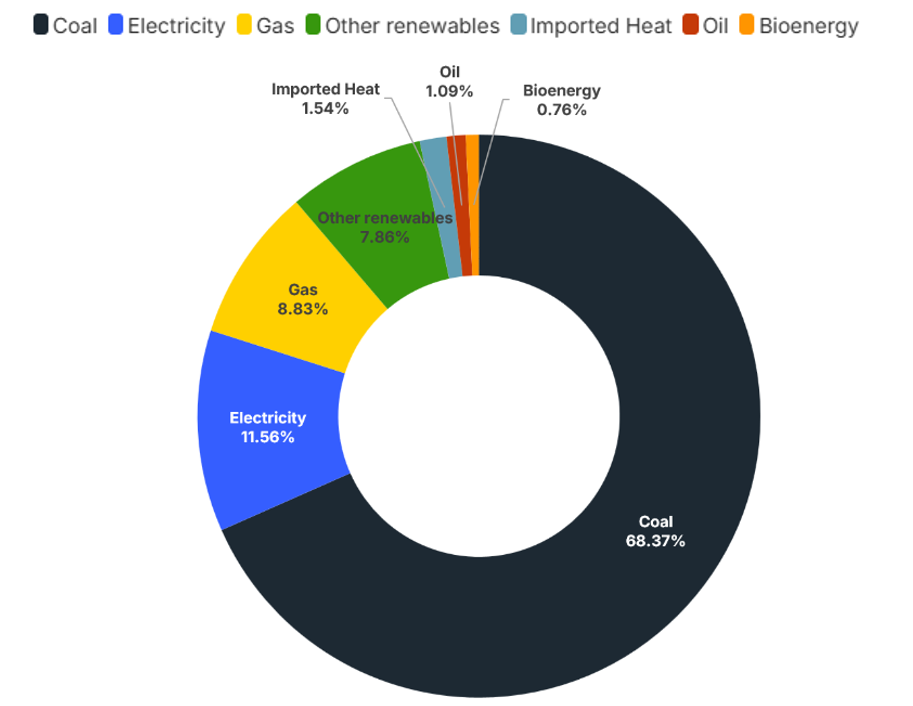
Electricity comprises less than 12% of the global steel industry’s vast energy consumption, making it a key target for further electrification and critical to steelmaking nations achieving climate targets.
The focus on decarbonising primary steelmaking and the hype around hydrogen have overshadowed the potential to electrify other processes in the steel value chain. The transition is already well advanced in secondary steelmaking where electric arc furnaces are used to melt scrap metal.
“Further opportunities exist across the downstream steel value chain, particularly through the electrification of process heat supplied by gas and other fossil fuels,” Mr Basirat says.
“Electrochemical ironmaking technologies are being developed to use electricity to remove oxygen directly from iron ore, potentially eliminating the need for carbon- or hydrogen-based reductants altogether. However, these technologies remain at an early stage of development.”
Generating the extreme heat (>1,000°C) needed for steelmaking takes up almost 70% of the sector’s total energy consumption. High-temperature processes require innovative and scaleable electrification technologies that can compete with their fossil fuel-based counterparts.
“Primary steelmaking presents a more complex challenge,” Mr Basirat says. “Hydrogen can enable indirect electrification by replacing fossil fuels as a reducing agent in direct reduced iron production.
“Hydrogen can also be used to generate process heat when burned, but its relatively low efficiency and high cost compared with direct use of electricity make it less attractive for heating applications.”
Sources of energy used in global steelmaking
As the share of renewables in electricity grids increases, adaptability becomes critical, making flexible technologies increasingly valuable.
“New electric steelmaking technologies can provide opportunities to adjust electricity consumption in response to system conditions, allowing plants to reduce or shift demand during periods of high electricity prices or peak system demand,” Mr Basirat says. “This flexibility can improve the economics of electrification while helping integrate higher shares of variable renewable electricity.”
However, the steel sector faces higher upfront investment requirements to make the transition, and often lacks the policy support and incentives available to other sectors, such as transportation via EVs and heat electrification in buildings via heat pumps.
“Annual investment in electrification is expected to increase from about USD320 billion in 2026 to about USD1 trillion in 2035,” Mr Basirat says. “However, industry is expected to account for less than 3% of the total investment, compared with much larger shares going to transport and buildings.
“The case for electrification extends beyond emissions reduction and energy efficiency. Recent global conflicts and disruptions to major fossil fuel trading routes have highlighted the energy security risks associated with dependence on imported coal, gas and other fossil fuels.”
While expanding secondary steelmaking will drive some electrification, along with the indirect impact of green hydrogen, electrifying heat processes in the downstream value chain will be critical. However, this will require targeted policy support, infrastructure investment and market incentives.
“Electrification should therefore be viewed not simply as a decarbonisation pathway for steel, but as an opportunity to improve energy efficiency, reduce fossil fuel dependence, strengthen energy security, and increase the flexibility and resilience of steel production,” Mr Basirat says.
Read the report: Electrification across the steelmaking value chain